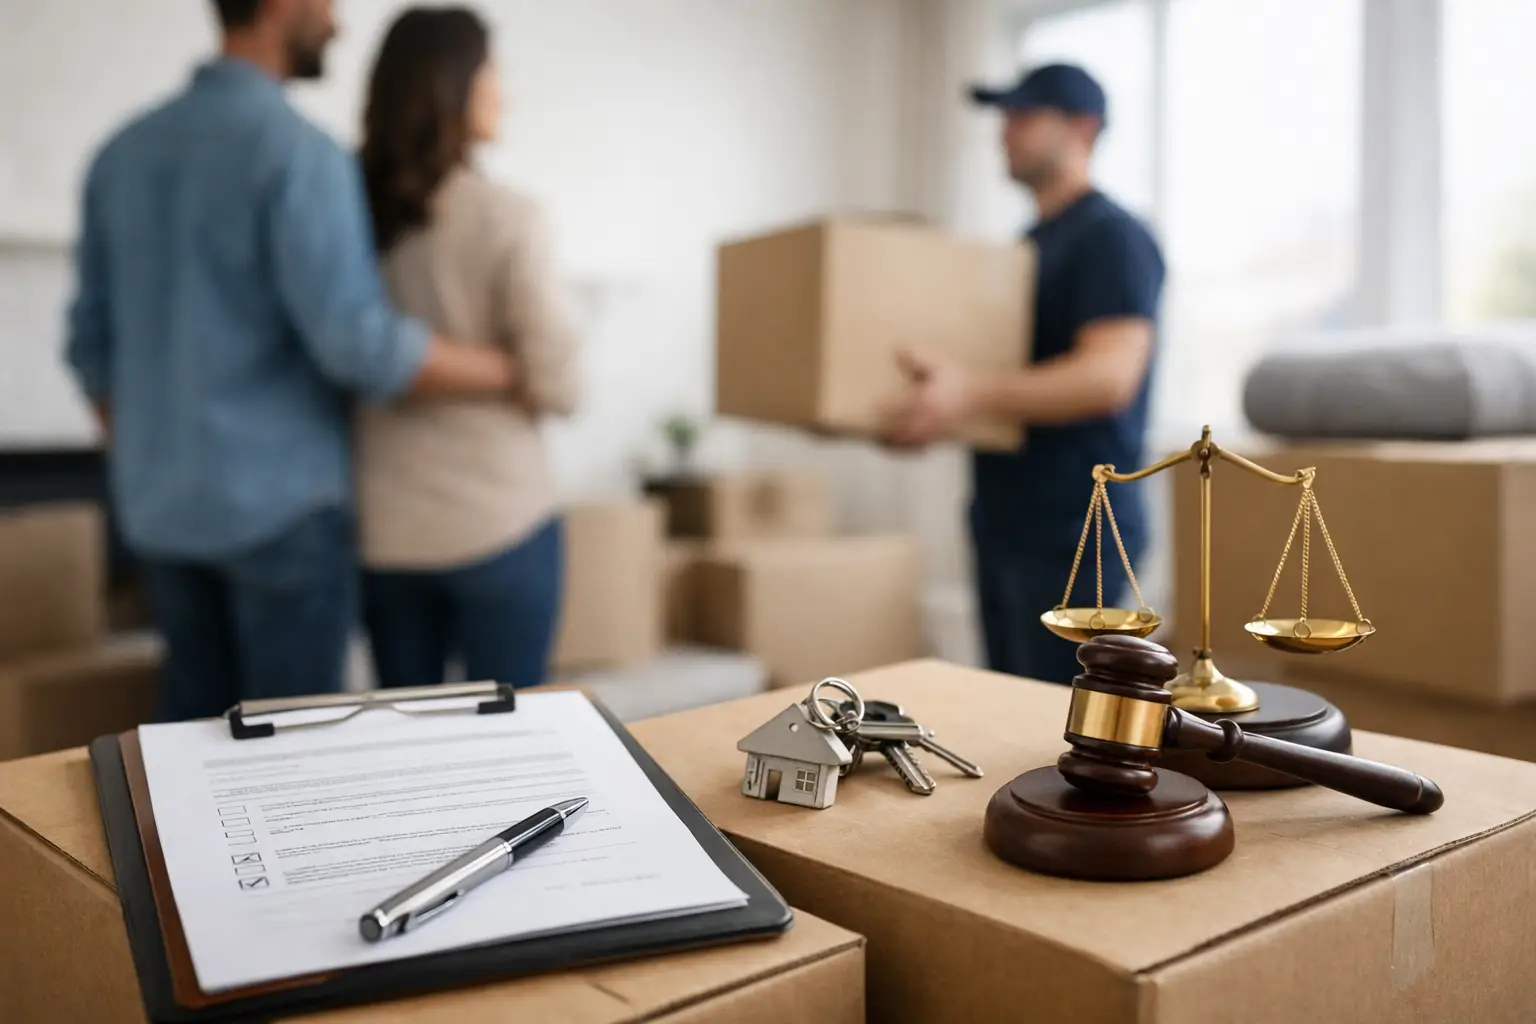
A dining table that has been in the family for 30 years, a computer needed for work on Monday, and a box of irreplaceable photographs do not carry the same risk. That is why moving insurance coverage deserves attention before the truck arrives, not after a damaged-item conversation begins. The paperwork can be confusing because a mover's liability, valuation protection, and an insurance policy are not always the same thing.
A clear plan starts with knowing what protection is included, what it actually pays for, and which belongings may need additional coverage. It also helps you make sensible decisions about packing, inventory, and claims while there is still time to prepare.
Moving insurance coverage starts with the terms
When people say "moving insurance," they often mean any protection for belongings during a relocation. In practice, there may be several layers. A moving company may provide a stated level of liability for items in its care. Your homeowners or renters policy may include limited protection away from home. A separate policy or endorsement may offer broader coverage for a particular move.
The distinction matters because basic mover liability can be calculated by an item's weight rather than its replacement value. That may provide only a modest payment for a lightweight but expensive item, such as a television, artwork, laptop, or designer chair. Valuation protection may improve the amount available if the mover is responsible, but it is still governed by the mover's contract, exclusions, and claims process.
Ask for the written terms before booking. Do not rely on a verbal description such as "your things are covered." Request an explanation of the coverage limit, deductible, claims deadline, exclusions, and how repairs or replacement values are decided. If a move crosses a state, provincial, or international border, the rules and available options can change.
Check what your mover includes
A reputable mover should be able to explain its standard liability and any optional valuation or protection plans in plain language. The goal is not simply to select the highest available amount. It is to understand the gap between what is included and the financial loss your household could reasonably absorb.
Start by confirming whether the mover is responsible only while items are on the truck or during the full service period. Loading, unloading, temporary storage, and handling by a third-party storage provider can each have different terms. If your move includes a storage stop, a delayed possession date, or a shared shipment, ask who has custody at every stage.
It is also worth asking how packed-by-owner boxes are handled. Movers may limit responsibility when they cannot verify what was inside a carton or whether it was packed securely. That does not mean you should automatically pay for full-service packing, but it does mean careful labeling and photographs become more valuable.
For a commercial move, the same question applies to office equipment, servers, files, and specialized furniture. Standard protection may not reflect the cost of business interruption, data recovery, or a replacement item that must be ordered quickly. A business owner or office manager should review the move plan with its existing commercial insurer before moving day.
Read exclusions before you need them
Coverage commonly has conditions. Damage caused by pre-existing wear, poor customer packing, mechanical failure, or natural events may be excluded or limited. High-value items can require advance declaration. Jewelry, cash, important documents, medications, and sentimental keepsakes may be unsuitable for the moving truck regardless of the policy language.
Keep essential and irreplaceable items with you when practical. This is not just an insurance decision. It reduces the chance that a missed deadline, delayed truck, or misplaced carton creates a much bigger problem.
Review your current home or renters policy
Your current policy may provide some off-premises or transit coverage, but assumptions can be costly. Call your insurer and describe the move, including origin, destination, dates, use of professional movers, and any temporary storage. Ask whether coverage applies to damage, theft, water exposure, and loss while belongings are in transit.
Then ask the more useful question: what is not covered? Some policies cover belongings only under limited circumstances or subject to the same deductible as a larger home claim. If the deductible is $1,000 and the likely damage is a broken $600 bookcase, filing a claim may not help. On the other hand, an accident affecting several valuable items could make additional protection worthwhile.
Your insurer may offer a moving endorsement, a scheduled-property option for specific valuables, or a temporary increase in personal-property coverage. The right choice depends on the value of your contents, the distance and complexity of the move, and how much risk you are willing to carry yourself.
Make an inventory that supports a claim
An inventory is useful even if you never file a claim. It keeps packing organized, helps identify missing boxes quickly, and gives you a realistic picture of how much coverage you need. For estate clear-outs and downsizing projects, it can also help families track items that are being distributed, donated, stored, or moved to a new residence.
Before packing, document higher-value belongings and the general condition of furniture. A simple phone-based record is usually enough if it is detailed and saved somewhere accessible outside the moving boxes. Include:
- Photos and short videos of furniture, electronics, artwork, and fragile items
- Brand names, model numbers, serial numbers, and receipts when available
- A room-by-room list of boxes with clear labels and destination rooms
- Notes on existing scratches, dents, or mechanical issues
- Copies of the estimate, bill of lading, inventory sheets, and coverage documents
For an item with a meaningful market value, obtain an appraisal or keep purchase documentation. Sentimental value is real, but most policies cannot compensate for it. A detailed record cannot replace a family photo album, yet it can make the practical side of a claim far easier to manage.
Reduce the chance of damage in the first place
Insurance is a financial backstop, not a packing strategy. The best outcome is still a move where nothing needs to be claimed. Use appropriately sized boxes, avoid overloading them, and cushion fragile items with proper packing material. Mark cartons containing fragile contents, but also describe the handling need when necessary, such as "keep upright" or "do not stack."
Disassemble furniture according to the mover's instructions and place screws, remotes, cords, and hardware in labeled bags. Take a photo before disconnecting electronics. If the mover is packing for you, point out delicate, antique, unusually heavy, or high-value items during the walkthrough so they can be noted before loading begins.
On delivery day, check items as they come off the truck. Look for visible damage before signing final paperwork whenever possible. If something is damaged or missing, note it directly on the delivery documents and take photographs. A calm, factual record made immediately is more useful than trying to reconstruct events a week later.
Know the claims process before moving day
Ask the mover how to submit a claim, what documents are required, and how quickly you must act. Deadlines can be short. Save emails, estimates, inventory sheets, and all communication about the issue. Do not discard damaged property or arrange repairs before confirming what the claims administrator needs, unless doing so is necessary to prevent further damage.
A claim may result in repair, replacement, or a settlement based on the coverage terms. That process can take time, particularly when an item needs an inspection or ownership records are incomplete. Clear documentation will not guarantee a preferred result, but it gives the claim a much stronger foundation.
For larger moves, complicated estates, or relocations involving storage and several parties, designate one person to hold the documents and communicate with the mover. A single point of contact prevents duplicate information and makes it easier to track decisions.
Before you choose a mover or accept a quote, set aside 15 minutes to compare the included protection with the value of what you are moving. That small planning step can help you pack with more care, ask better questions, and move forward knowing exactly where your coverage begins and ends.

